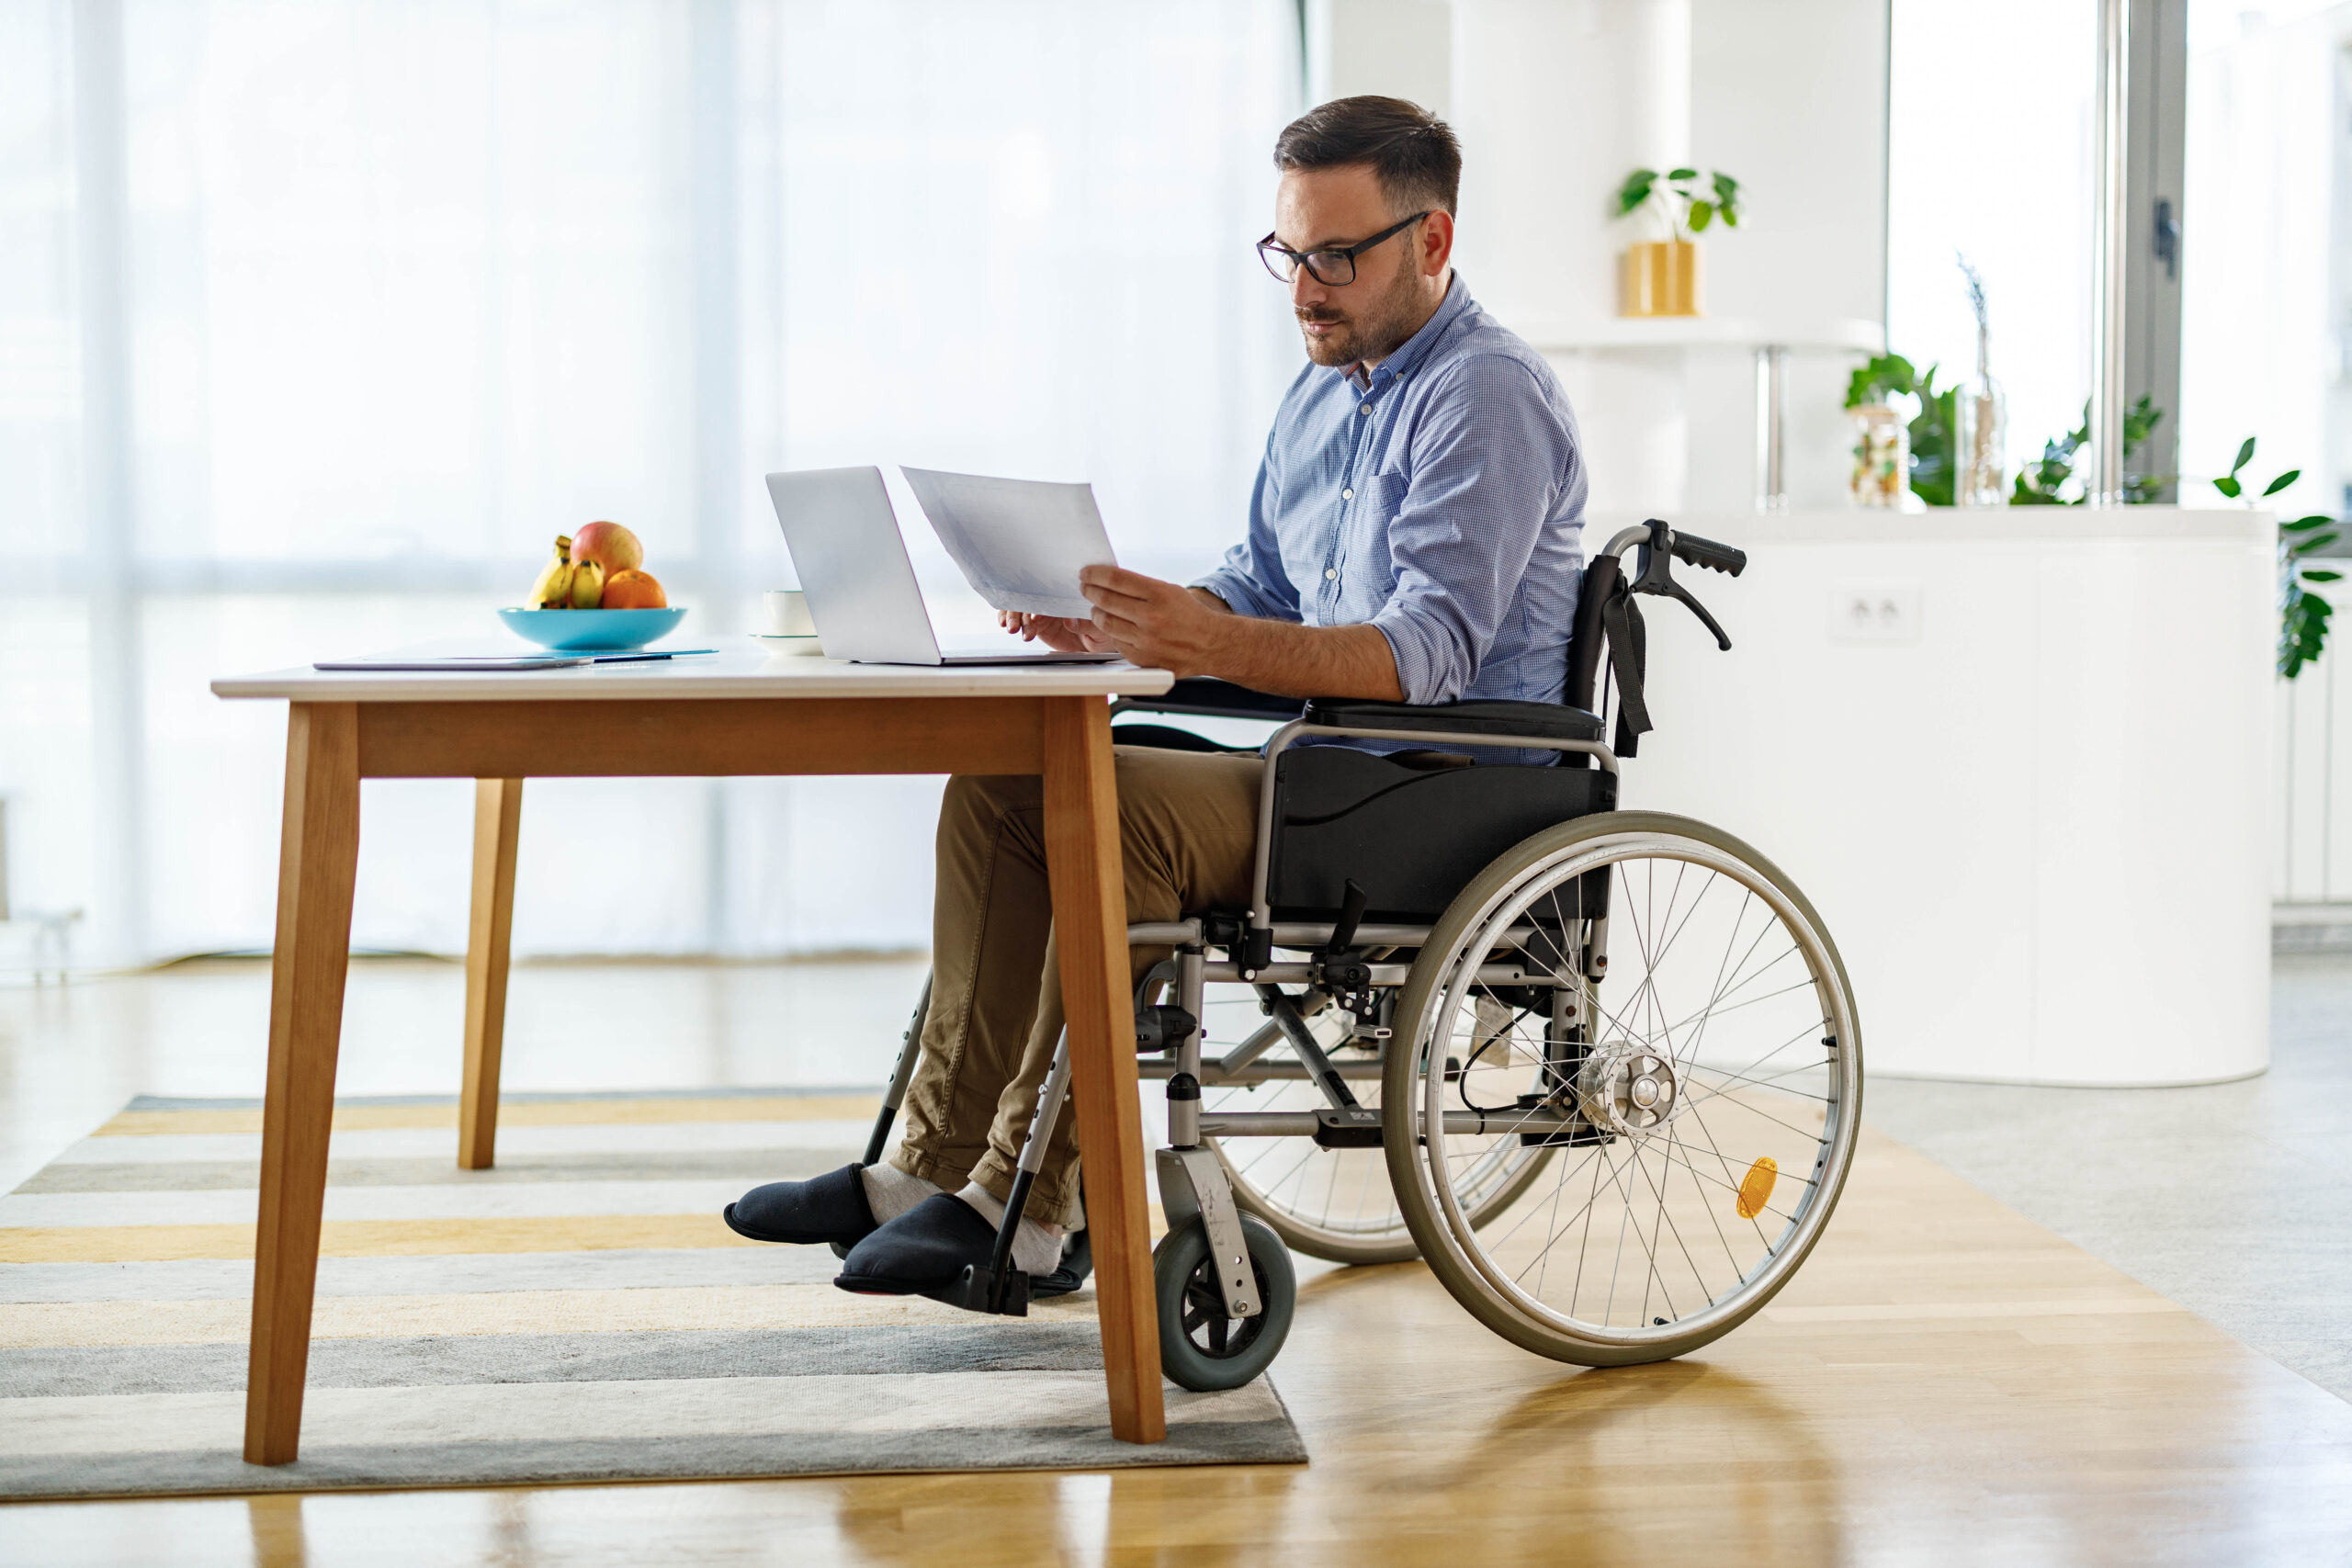
Disability insurance is designed to replace part of your income if an illness or injury keeps you from working. It does not usually pay your medical bills; health insurance is built for that. Disability coverage is meant to help with the rent or mortgage, groceries, utilities and other expenses that continue even when a paycheck stops.
The two main forms are short-term disability insurance and long-term disability insurance. Short-term coverage generally pays benefits for a limited period—often a few months—while long-term coverage can continue for years, depending on the policy. The difference is not just how long a policy pays. The waiting period, definition of disability, benefit amount and exclusions can determine whether the coverage is useful when you need it.
Short-term vs. long-term disability insurance: the main differences

Short-term disability insurance is designed to cover a temporary interruption in earnings. Policies commonly replace a portion of income for around three to six months, although benefit periods vary. Depending on the plan, coverage may begin after a short elimination period and may apply to pregnancy, recovery from surgery, illness or an injury that meets the policy’s definition of disability.
Long-term disability insurance is designed for a more extended loss of earning ability. Benefits may begin after a longer waiting period—often 90 days or 180 days—and may continue for a set number of years or until a stated retirement age. Some plans coordinate with short-term disability so that the short-term benefit pays first and the long-term benefit begins after its elimination period.
The National Association of Insurance Commissioners says short-term policies typically replace part of salary for three to six months, while long-term coverage may begin around six months after a disability and continue for years or even to retirement age. Those are general descriptions, not guaranteed terms for every policy. The actual contract controls.
Neither type automatically pays because someone is sick or injured. The claimant must meet the policy’s definition of disability and satisfy any waiting period, medical documentation and other requirements. Some policies cover both illness and accidents; accident-only coverage is narrower and may leave a major gap.
Read the policy’s NAIC consumer guide to disability insurance and the Maine Bureau of Insurance policy-feature guide before comparing benefits.
How much disability insurance pays—and when benefits begin

Many disability policies replace a percentage of covered earnings rather than the full paycheck. The NAIC notes that a typical benefit is around 60% of pre-disability earned income, but the actual amount depends on the contract, income documentation, policy limits and other benefits. A policy may set a maximum monthly payment even when the stated replacement percentage is higher.
The elimination period is the time you must remain disabled before benefits can begin. A 30-day waiting period is common in some short-term plans; long-term policies often use longer periods such as 90 or 180 days. Longer waiting periods can reduce premiums, but they also mean you need enough savings or other coverage to manage the gap.
The benefit period is how long payments can continue once a claim is approved. It might be a few months, two years, five years or until a specified retirement age. A policy with a low premium may have a shorter benefit period, a longer waiting period or a more restrictive disability definition. Compare the full terms rather than choosing by monthly price alone.
Another key detail is how the policy defines disability. An own-occupation definition may pay if you cannot perform the substantial duties of your specific occupation, subject to the contract. An any-occupation definition can be stricter, requiring that you be unable to work in another occupation for which your education, training or experience reasonably qualifies you. Some contracts change from own-occupation to any-occupation after a set period.
Look for partial or residual disability benefits too. These may pay a reduced benefit if you can return to work part-time or perform some duties but still suffer a qualifying loss of income. Other policy options can include cost-of-living adjustments, future increases in coverage, waiver of premium and rehabilitation benefits.
Taxes can affect the amount you keep. In general, benefits from coverage paid entirely with after-tax dollars by the employee are often received tax-free, while benefits tied to employer-paid or pre-tax premiums may be taxable. Employer plans can involve shared premium payments and special rules. Check the plan documents and the IRS guidance in Publication 525, Taxable and Nontaxable Income, or ask a qualified tax professional about your situation.
How to choose coverage through work or on your own

If your employer offers disability insurance, find out whether the coverage is automatic or optional, how much income it replaces, what the maximum monthly benefit is and whether the employer pays the premium. Ask whether the plan continues if you change jobs or leave the company. Group coverage can be a useful starting point, but the benefit may be capped and may not follow you when employment ends.
If you are self-employed, a contractor or a small-business owner, an individual policy may be the main way to protect your earnings. Insurers may review income history, occupation, health information and the amount of coverage requested. Some policies offer residual benefits that are particularly relevant when a person can return to work only part-time or loses income while rebuilding a business.
Before buying, estimate your essential monthly expenses and compare them with emergency savings, paid leave, employer coverage and any public benefits you may qualify for. Then compare policies using the same assumptions: monthly benefit, elimination period, benefit period, definition of disability, exclusions, offsets and premium. Ask how the policy treats recurring conditions, mental-health claims, partial disability and changes in earnings.
Do not assume Social Security Disability Insurance will replace your full paycheck or begin immediately. It has its own eligibility rules and application process. Private disability coverage may offset or coordinate with other benefits, so check the contract before assuming you can simply add every payment together.
The right policy is not necessarily the one with the biggest advertised percentage or the lowest price. It is the one whose definition of disability, benefit amount and duration fit the income you need to protect—and whose waiting period you can realistically afford. Reading those details before you enroll is far easier than discovering a coverage gap after you cannot work.

Leave a Reply