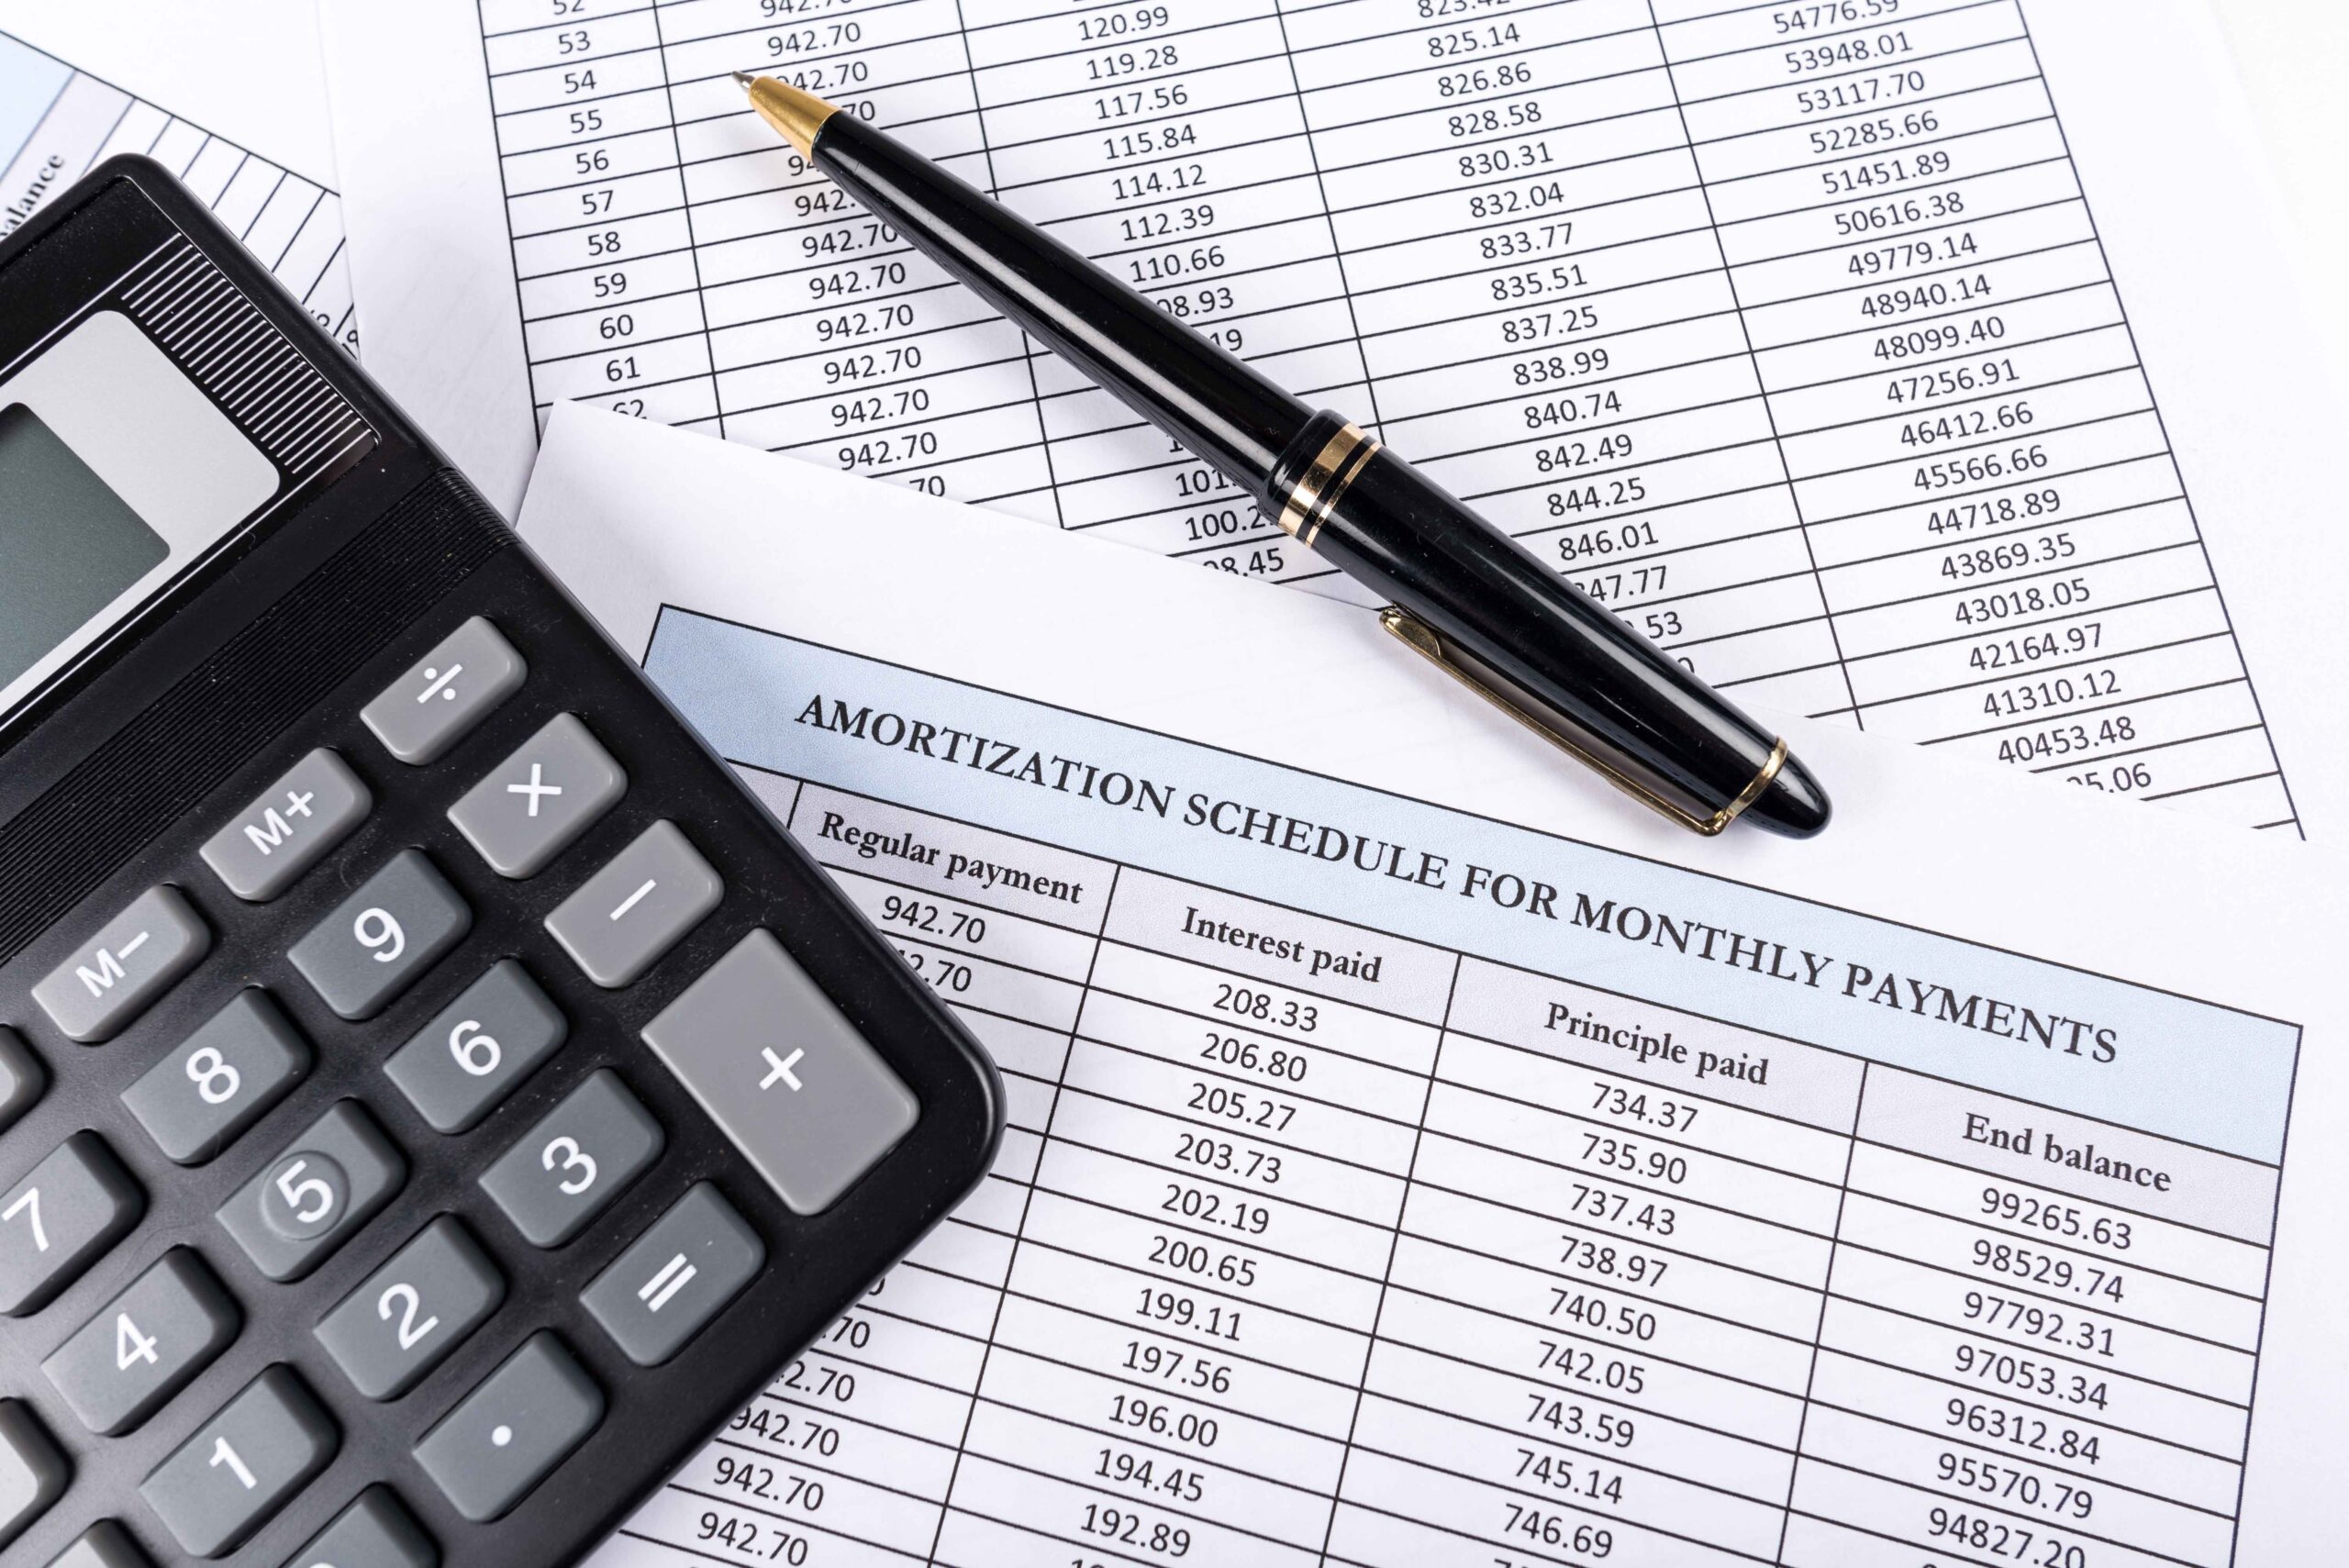
A mortgage recast lets an eligible homeowner make a large payment toward the loan principal and ask the lender or servicer to recalculate the monthly payment using the smaller balance. The interest rate and remaining loan term generally stay the same, but the required principal-and-interest payment falls because the lender is spreading a lower balance over the time left on the loan.
It can be useful after receiving an inheritance, selling another property, using savings or making another large payment. Unlike refinancing, a recast does not replace the mortgage with a new loan. That can make it a simpler way to reduce the monthly payment when the current interest rate is worth keeping. But not every loan qualifies, and a recast does not remove property taxes, homeowners insurance or mortgage insurance from the monthly housing bill.
How a mortgage recast works after a lump-sum payment

First, the borrower makes a qualifying lump-sum payment that reduces the mortgage principal. The borrower then requests a recast from the mortgage servicer. If the loan and payment meet the servicer’s rules, the company recalculates the scheduled principal-and-interest payment based on the new balance, the existing interest rate and the remaining term.
For example, imagine a homeowner has a fixed-rate mortgage with 20 years remaining and uses $50,000 of savings to reduce the principal. After the recast, the monthly principal-and-interest payment is recalculated using the smaller balance over those same 20 years. The interest rate does not reset, and the loan does not become a new 30-year mortgage.
The payment reduction depends on the original balance, the lump sum, the interest rate and how much time remains. A larger principal payment generally creates a larger reduction, but there is no single amount that guarantees a specific monthly savings figure. The servicer can provide an estimate before the borrower commits.
A recast usually affects only the principal-and-interest portion of the payment. Property taxes, homeowners insurance, homeowners association dues and any mortgage insurance are separate costs. If those expenses are collected through an escrow account, the total monthly payment may still change when escrow is recalculated, even though the recast itself does not change them.
Chase explains that a recast can lower a payment without refinancing and that the existing interest rate remains in place. Its mortgage recast overview also notes that eligibility and process requirements apply. Other servicers may have different minimum lump sums, fees and documentation requirements.
Mortgage recast vs. refinance vs. extra principal payments

A recast keeps the existing mortgage. The borrower pays down principal, pays any required recast fee and asks the servicer to lower the scheduled payment. The current rate and remaining term generally stay in place. It is often attractive when the existing rate is lower than the rates available for a new mortgage, or when the borrower wants to avoid the costs and paperwork of a refinance.
A refinance replaces the current mortgage with a new loan. It can change the interest rate, term, loan type or borrower structure, but it usually involves a new application, underwriting, closing costs and possibly an appraisal. Refinancing can be useful when a borrower wants a lower rate or different loan terms, but the savings must be weighed against the cost of obtaining the new loan.
An extra principal payment without a recast reduces the loan balance, but the required monthly payment usually remains the same. Because the borrower keeps making the original payment against a smaller balance, the loan may be paid off sooner and total interest can fall. This can be a better fit for someone whose goal is to become mortgage-free faster rather than reduce the required monthly bill.
The choice depends on the goal. If monthly cash flow is the priority, a recast may help. If the goal is a lower rate or a different term, compare refinancing. If the goal is to shorten the payoff timeline and save interest, an extra principal payment without lowering the payment may be worth considering.
Interest-rate conditions matter too. The yield on the 10-year Treasury is one of several benchmarks that influence mortgage pricing, although mortgage rates do not move one-for-one with Treasury yields. The Immortal Times explains the relationship in Treasury Yields Explained: What They Mean for Your Money.
Who qualifies for a mortgage recast—and what to ask the lender

Eligibility depends on the loan type, investor or guarantor rules and the servicer’s policies. Some conventional mortgages allow recasting, while many government-backed loan programs do not offer the same option. Do not assume that a loan qualifies simply because the lender advertises recasting for other customers.
Before sending a lump sum, contact the company that services the mortgage and ask:
- Does this exact loan qualify for a recast?
- What is the minimum principal payment?
- Is there a recast fee, and how much is it?
- Must the loan be current, and how many payments must have been made?
- How long does the process take after the principal payment clears?
- Will the interest rate, maturity date and escrow payment change?
- Can the servicer provide a written estimate of the new principal-and-interest payment?
Ask how the lump sum must be submitted. A payment made through the normal monthly-payment portal may not automatically trigger a recast. The servicer may require a separate application, signed request or specific payment instructions. Keep confirmation of the amount applied to principal and the new amortization schedule.
Also consider liquidity. Money used for a recast becomes home equity, which is not as easy to access as cash in a savings account. Do not use an emergency fund or money needed for near-term expenses just to reduce a monthly mortgage payment. Compare the expected payment reduction with other uses for the money, including high-interest debt and essential savings.
A mortgage recast can be a practical middle ground: it lowers the required principal-and-interest payment without replacing a mortgage whose rate and terms you want to keep. The important step is confirming eligibility and the exact cost with the servicer before making a large payment. The lender’s written calculation—not a generic online estimate—should guide the decision.

Leave a Reply