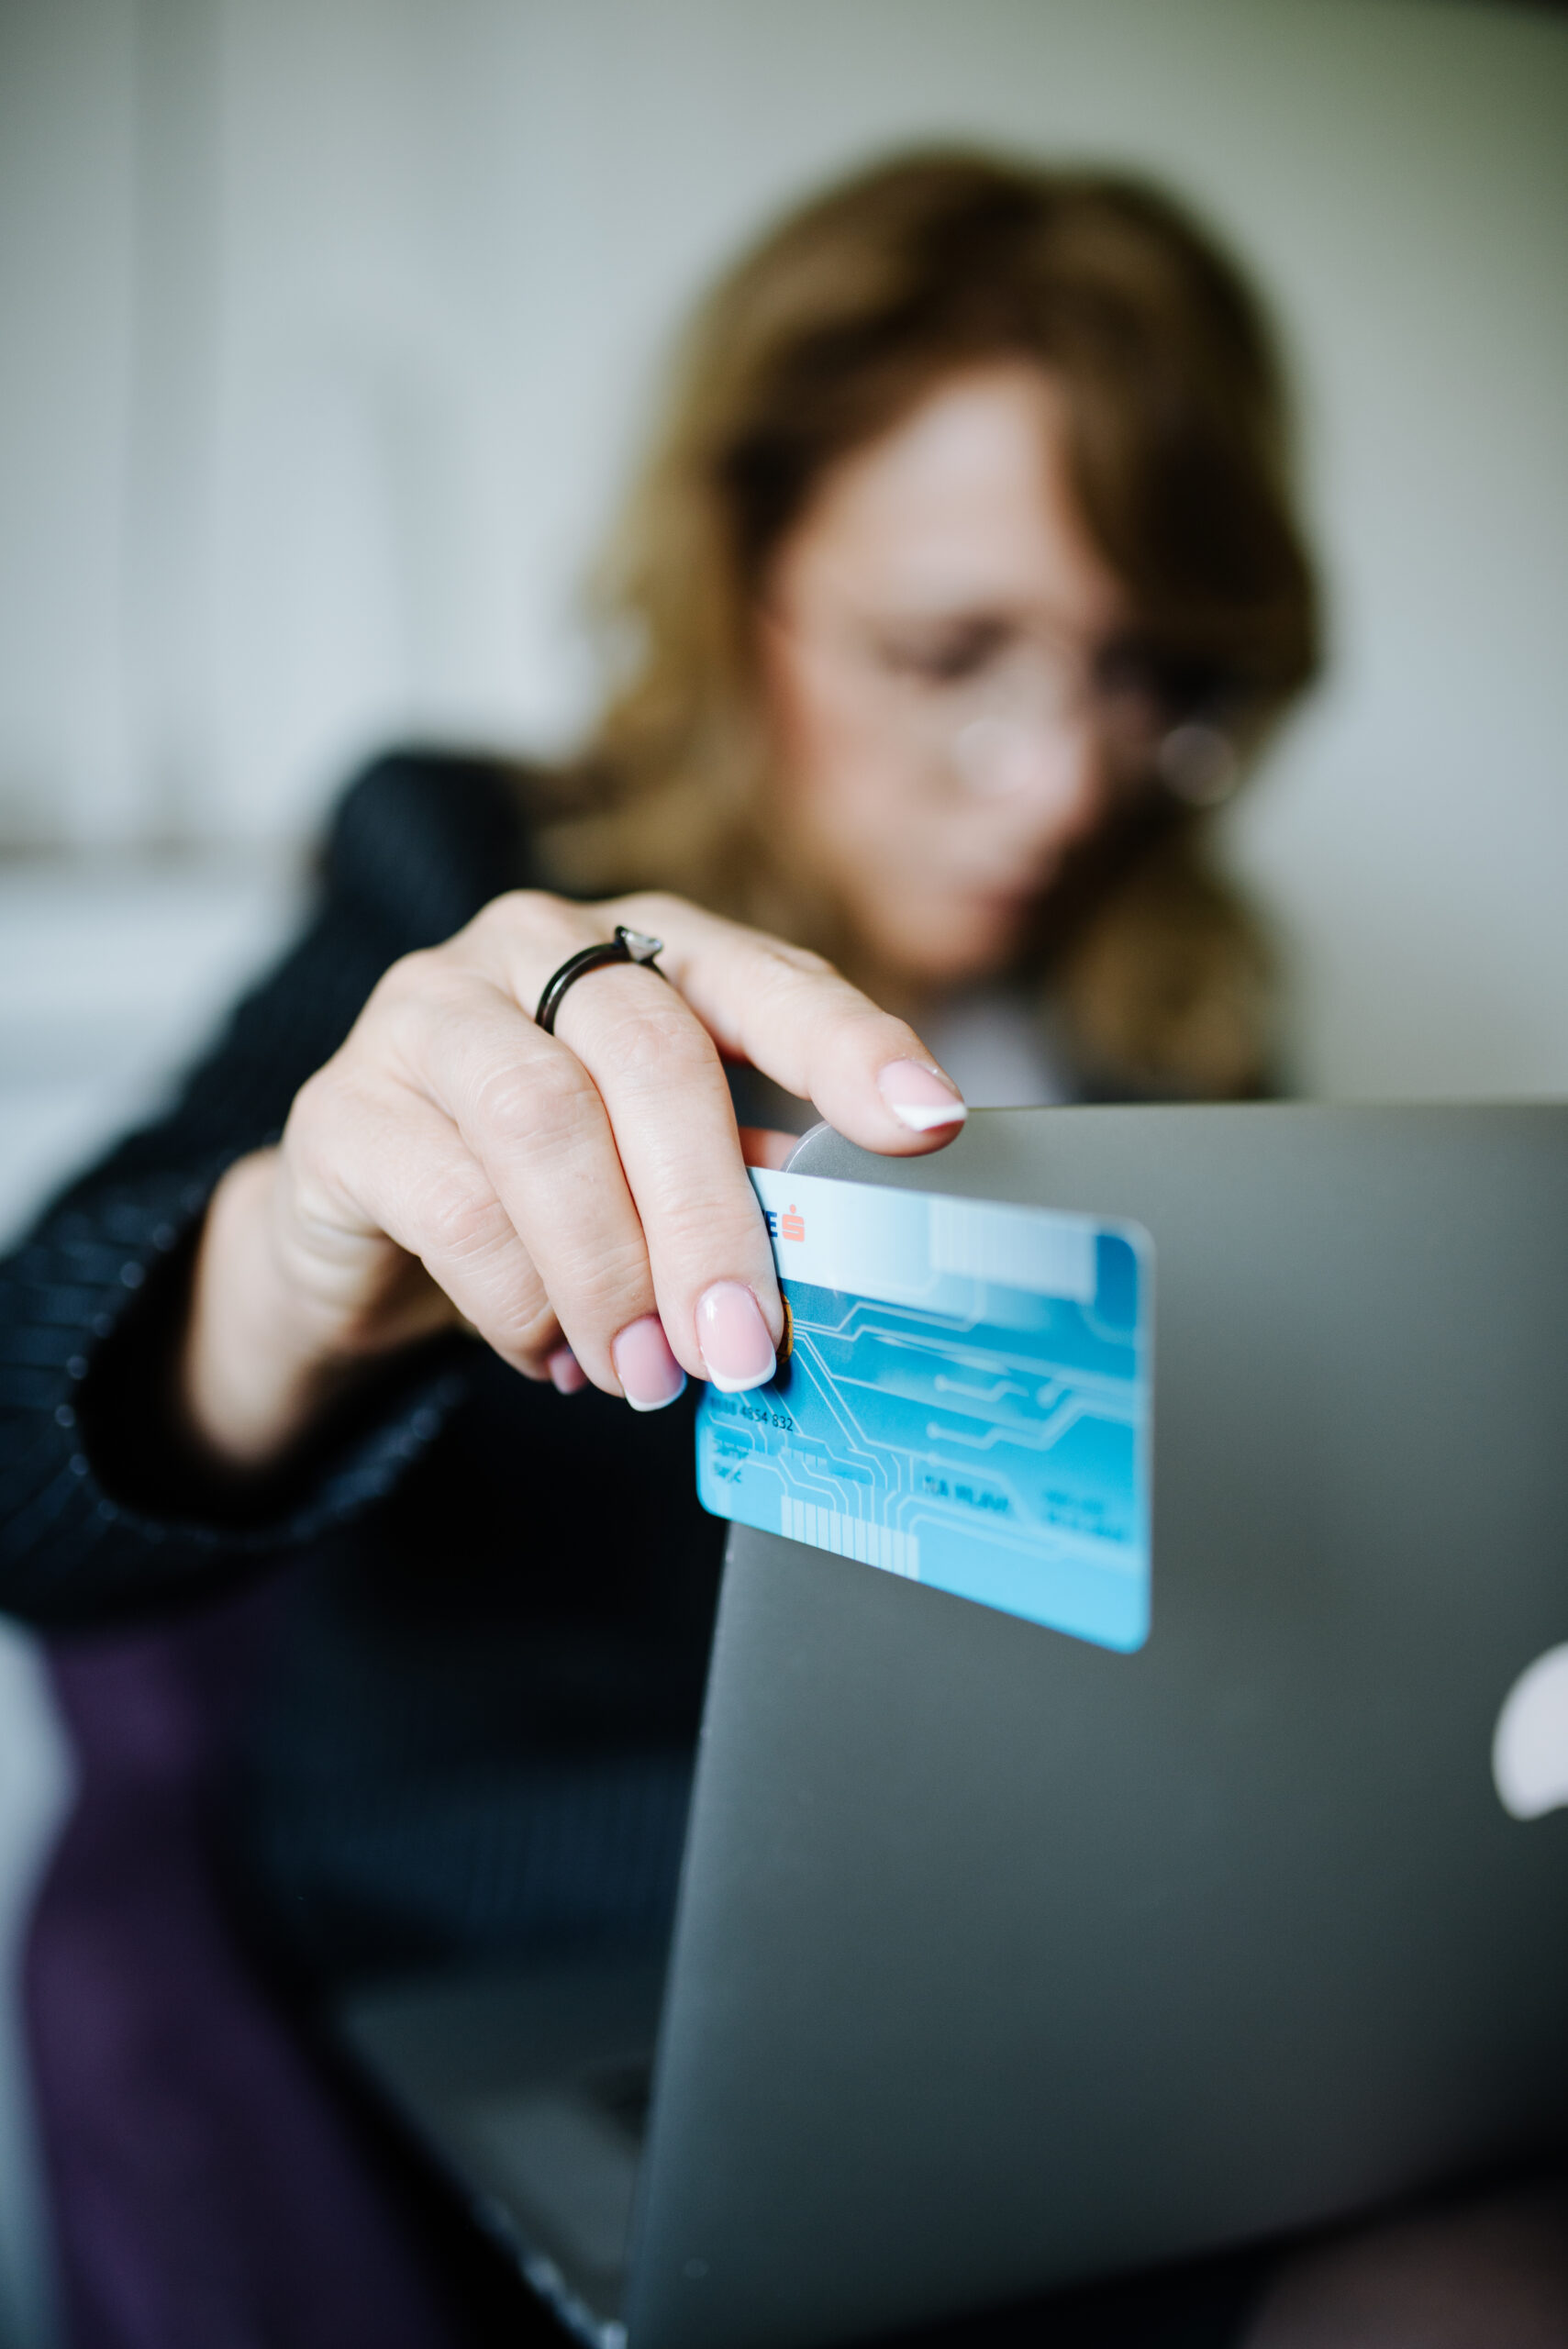
When a credit-card purchase goes wrong, the phrase “purchase protection” can mean several different things. A billing error, an unauthorized transaction, a merchant dispute and an item damaged after delivery are not necessarily handled under the same rules. Knowing which problem you have—and acting before the relevant deadline—can make a significant difference.
First, identify what kind of problem you have
A billing error may include a charge for the wrong amount, a transaction you did not make, a payment the issuer failed to credit, or a purchase that was never delivered. An unauthorized charge raises a separate question: did you or an authorized user approve the transaction? A merchant dispute may involve goods or services that were defective, misrepresented or not provided as promised.
Some credit cards also advertise purchase protection, extended warranties or return protection. Those are often benefits supplied under the card’s terms, and they can have exclusions, claim limits and filing windows. They are not the same thing as the federal billing-error rights that apply to qualifying disputes.
How to dispute a billing error
The Consumer Financial Protection Bureau advises cardholders to contact the issuer promptly and send a written billing-error notice within 60 calendar days after the statement containing the error was sent. The billing-dispute address may differ from the payment address, so follow the instructions on the statement or issuer’s website.
In the written notice, identify the transaction, explain why you believe it is wrong and include copies of relevant supporting records. Keep the original documents and a copy of everything you send. The issuer generally must acknowledge the dispute within 30 days unless it has already completed the required investigation, and it generally must resolve the matter within two billing cycles, subject to the law’s requirements.
What happens while the issuer investigates?
For a qualifying billing-error dispute under the Fair Credit Billing Act, you generally do not have to pay the disputed amount or related finance charges while the issuer investigates. You must still pay the undisputed portion of your bill on time. Continue reviewing statements and follow the issuer’s instructions so a legitimate balance does not become delinquent.
If the issuer decides the charge is correct, it must explain the decision and tell you what you owe. If it determines the billing error occurred, it must correct the account. Do not assume that simply making a phone call automatically preserves every legal right; the written notice and deadline are important.
What if the purchase was defective or never arrived?

Start by contacting the merchant and keeping a record of the attempt to resolve the problem. Save the order confirmation, delivery tracking, product description, return policy, photographs and any messages exchanged. If the merchant does not resolve the issue, contact the card issuer and ask which dispute process applies.
Some disputes involving goods or services are treated differently from a billing error. The CFPB notes that a defective purchase may require a different dispute process. Certain federal “claims and defenses” rights can also depend on conditions such as the purchase location, the amount paid and whether the cardholder first tried to resolve the issue with the merchant. Do not assume every unhappy purchase automatically qualifies for a chargeback.
Unauthorized charges: act quickly
If you see a transaction you did not authorize, contact the issuer immediately using the number on the back of the card or the official app. Lock or freeze the card if that feature is available, ask whether a replacement is needed and review recent transactions for other unfamiliar activity. Change compromised online-account credentials and enable multi-factor authentication where possible.
Federal law generally limits a credit-card holder’s liability for unauthorized use, but timing and the circumstances matter. The protections for credit cards differ from those for debit cards, so do not assume the rules are identical. Follow the issuer’s instructions and submit any required written notice promptly.
Keep a clean record of the dispute
- Save the original receipt, order confirmation and statement.
- Record the date, time and name or reference number for every call.
- Use the issuer’s designated billing-dispute address or approved online process.
- Send copies, not irreplaceable originals, unless specifically instructed otherwise.
- Pay the undisputed portion of the balance by its due date.
- Review the next statements to confirm the correction or final decision.
Understand the limits of card “purchase protection”
Optional card benefits can be useful, but they are contract benefits, not a universal guarantee. Coverage may exclude certain products, used items, losses caused by ordinary wear, or purchases that do not meet documentation requirements. Some benefits require a claim within a short period and may reimburse only up to a stated amount after other coverage is considered.
Before relying on a benefit, download the current guide to benefits for your specific card. Confirm what counts as an eligible purchase, what proof is required, how to file and whether the benefit is primary or secondary to another policy.
The bottom line
Credit-card protections are strongest when you use the correct process and meet the deadline. For a billing error, the CFPB says to send a written notice within 60 days of the statement that first showed the problem. For unauthorized charges, contact the issuer immediately. For defective goods or optional purchase benefits, check the specific rules and keep thorough records. This article is general consumer information, not legal advice about an individual claim.
Related reading: How to Review a Subscription App Free Trial; FTC Affiliate Marketing Disclosure Rules.
Sources: CFPB: How to dispute a credit-card charge; CFPB: How to fix mistakes in a credit-card bill; CFPB: Credit-card consumer resources.

Leave a Reply